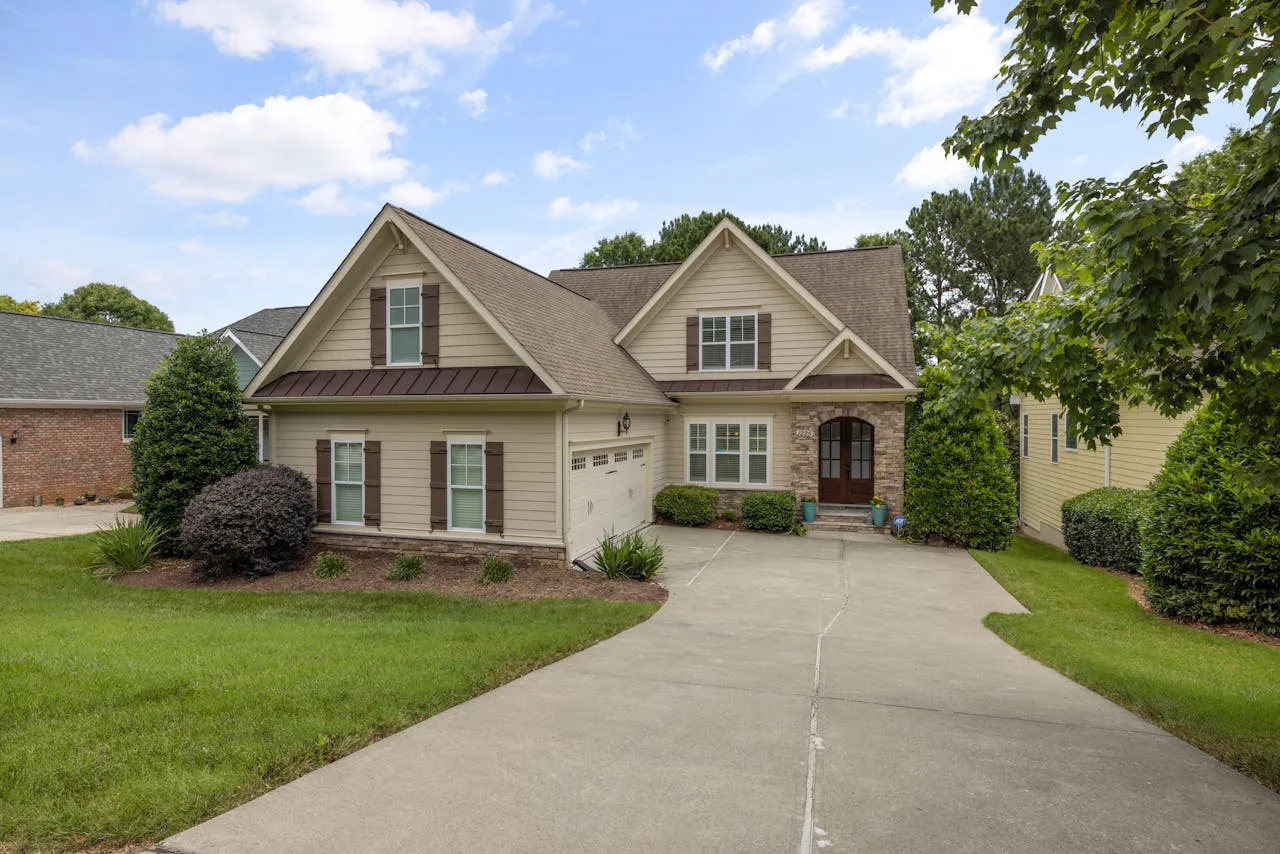
Possible roof damage
- Marked, bruised or fractured shingles
- Broken tiles or damaged roof panels
- Dented vents and other metal components
- Damaged flashing or roof penetrations
- Gutter and downspout damage
- New openings that allow water entry

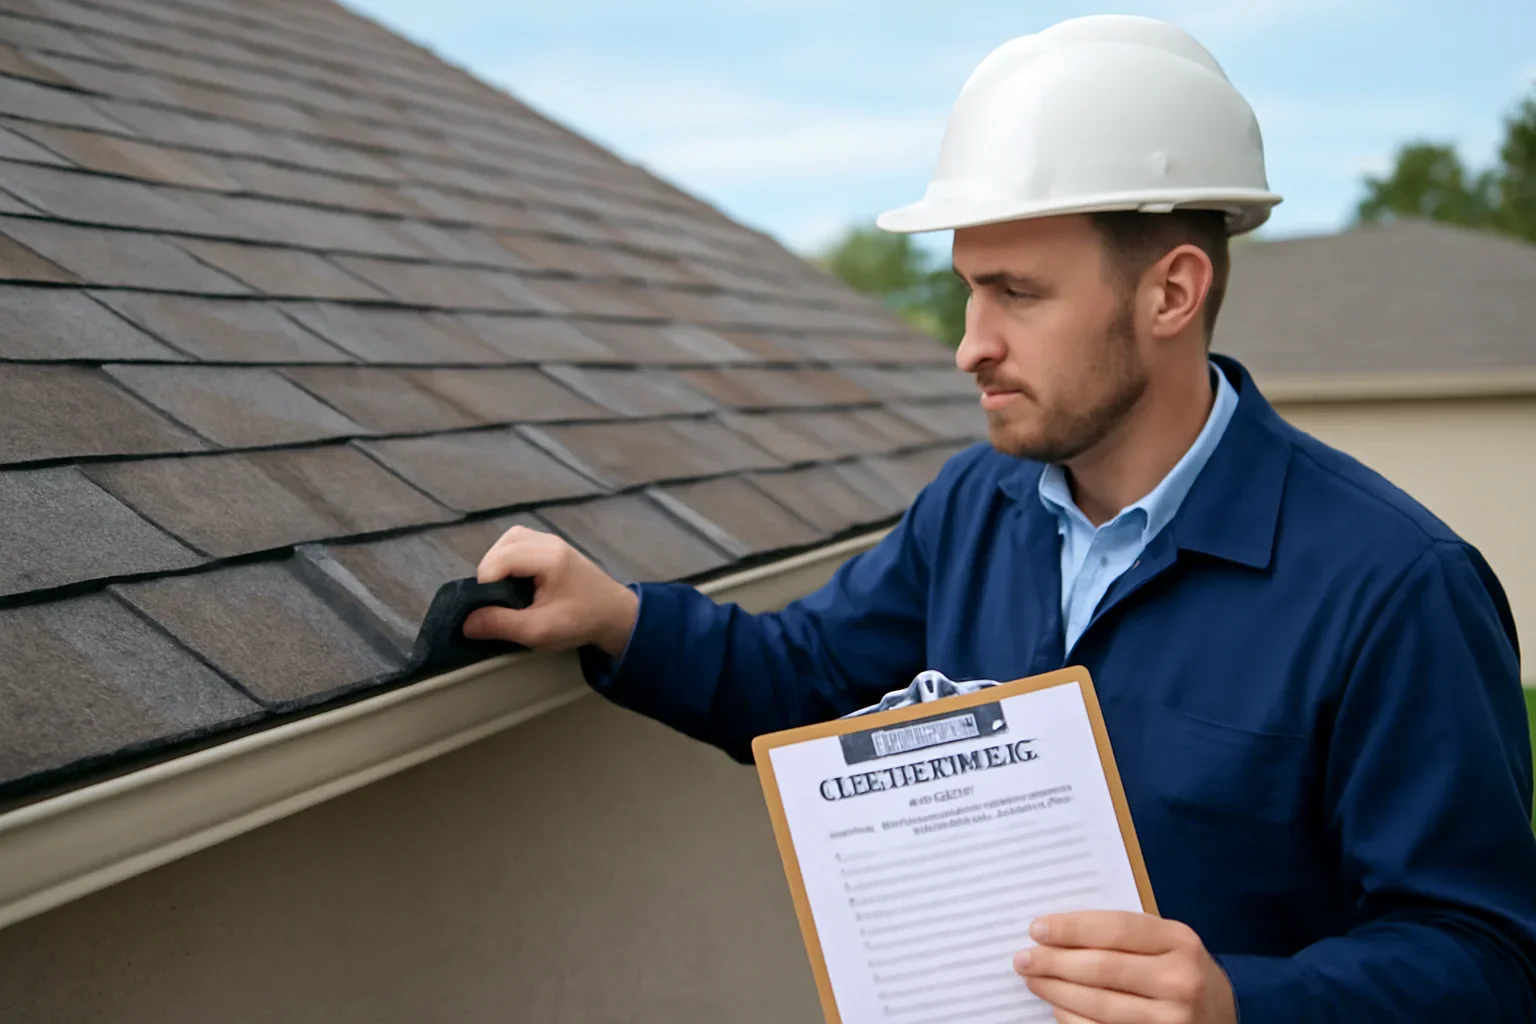
When one hailstorm affects roofing, siding, gutters and exterior details, the damage should be documented as one event while each building component receives its own professional assessment and written repair scope.
The short answer
Hail damage to a roof and siding should be assessed as connected parts of one exterior loss, even when different crews complete the work. The process normally includes safe documentation, insurer notification, professional roof and siding inspections, temporary protection when needed, separate repair estimates and a coordinated construction schedule.
The roofing contractor handles the roof system. A siding or exterior contractor addresses damaged wall cladding and associated trim. A general restoration contractor may coordinate both scopes. Coverage, deductibles, limits and claim approval remain decisions made by the insurer under the policy.
Understanding the loss
Yes. Wind-driven hail can affect several sides and surfaces during the same event. Damage patterns may vary because roof slopes and wall elevations face the storm at different angles.
Homeowners should not climb onto a storm-damaged roof. Take photographs from a safe location when conditions permit, then arrange assessment by qualified professionals.
Immediate response
Begin with personal safety, reasonable property protection and an accurate record of what happened.
The hail-damage roof insurance claims guide explains the broader reporting and claim process.
Complete exterior assessment
Hail does not always strike every building surface evenly. One roof slope may show impact while another appears less affected. A wind-facing siding elevation may sustain direct damage while a sheltered wall remains unchanged.
The purpose is to document the event accurately—not to assume that every exterior component requires replacement. A professional roof inspection for insurance can be coordinated with a separate siding assessment.
Specialist responsibilities
A qualified roofer assesses the roof system and records the condition of its materials and components.
The roofer should distinguish storm-related observations from aging, wear and maintenance conditions.
The exterior contractor assesses the wall cladding, transitions and related components.
Contractors document physical conditions. The insurer determines how cosmetic and functional damage are treated under the policy.
Regina homeowners can review professional siding repair and replacement services when comparing contractors for hail-damaged wall cladding.
Clear pricing
Separate line items are usually helpful even when one contractor manages the entire project. Clear scopes allow the homeowner and insurer to understand what belongs to each building system.
| Scope | Items that may be included | Purpose |
|---|---|---|
| Roofing estimate | Removal, underlayment, replacement roofing, flashing, vents, ridge materials, roof drainage, disposal and labour. | Repair the roof system and restore weather protection. |
| Siding estimate | Removal, replacement cladding, trim, corners, openings, fasteners, house wrap work where required, disposal and labour. | Restore affected wall cladding and associated details. |
| Shared project items | Scaffolding, access, site protection, permits, material storage, gutter work, painting, cleanup and interior repairs. | Support work that may affect more than one trade or building component. |
The roof and siding documents should identify their own materials, quantities and responsibilities while also explaining shared access, flashing, gutter and transition work.

Claim records
Documentation should describe what happened, which surfaces were affected and what protective or repair work followed.
Use the detailed checklist for documenting roof damage for an insurance claim to organize roof-specific photographs and records.
Do not remove siding, roofing or other exterior materials unless emergency protection or properly authorized work requires removal.
Construction sequence
The final sequence depends on exposure, weather, access, permit requirements, material availability and the way exterior components meet.
Critical transition points
Roofing and exterior walls meet at several locations. If roofing and siding crews work independently, responsibility for these details may become unclear.
Step flashing, wall flashing, lower roof intersections and cladding transitions may involve both crews.
Gutters, fascia, soffits and drip-edge details may need removal or protection during roofing or siding work.
Window surrounds, doors, penetrations and exterior trim must be integrated with the surrounding wall assembly.
Identify who removes existing components, installs flashing, reinstalls siding, replaces gutters, protects completed work, inspects transition points and provides each warranty.
Product matching
Older siding may no longer be manufactured in the original colour, texture, profile or dimensions. A siding contractor can document the existing product and investigate available replacement options.
The insurer evaluates matching and replacement concerns under the policy and applicable requirements. A visible difference does not automatically mean every elevation will be replaced, but the concern should be documented and the insurer’s decision requested in writing.

Physical repair decision
No single answer applies to every roof. Hail does not automatically mean that a complete roof replacement is physically necessary or covered by insurance.
Shingles, tile, metal and membrane systems respond differently to impact.
The number, severity and locations of affected areas influence repairability.
Age, wear, previous repairs and unrelated defects must be distinguished from storm damage.
Replacement materials and manufacturer requirements can affect the physical repair approach.
Read the detailed comparison of roof repair versus roof replacement for insurance. The contractor recommends a physical repair approach; the insurer determines whether and how the policy responds.
One project lead
A full-service restoration or general construction company may organize several trades while providing the homeowner with one project schedule and primary contact.
Roofers, siding installers, gutter crews, painters, window professionals and interior restoration teams may be scheduled through one project lead.
The coordinator can organize material orders, storage, scaffolding, inspections, site access and protection of finished work.
Inspection findings, estimates, change orders, additional damage and closeout records can be organized across the complete project.
Which work is completed in-house? Which trades are subcontracted? Who is responsible for each scope? Who coordinates permits, supplements, inspections, cleanup and warranties?
Regina property owners can review KB Better Construction when comparing contractors that coordinate roofing, siding and property-restoration services.
Representative example
Imagine that a hailstorm affects a west-facing roof slope and two siding elevations. The roof inspection identifies damaged shingles and marked metal vents. The siding assessment records cracked panels and impact marks around a window.
It does not establish insurance coverage and does not mean that every hail event requires roof or siding replacement.
Insurance responsibilities
Contractor findings help describe the physical damage and proposed repairs. The insurer reviews the reported event and applies the policy.
The roof insurance claim process provides a general overview of reporting, assessment and settlement stages. A contractor should not promise that an insurer will approve a roof, siding or matching claim.
Before authorization
Do not sign a contract that leaves the repair scope blank or makes the entire construction agreement dependent on an unknown future insurance settlement.
Independent resources
These organizations provide additional information about hail, property resilience and the insurance complaint process.
Frequently asked questions
Yes. Wind direction, building shape, material type, surface angle and exposure can create different damage patterns across the same property.
They should be treated as connected parts of the same exterior event, even when different specialists inspect and repair each surface.
Some contractors perform both services directly or coordinate specialized crews. Confirm responsibilities, insurance, subcontracting and warranty terms in writing.
No. The appropriate response depends on the siding material, the nature and extent of damage, repairability and the professional assessment.
Not automatically. The insurer evaluates the policy, affected areas, repairability, material availability and matching concerns before making its decision.
Ask the insurer. Emergency protection may be reasonably necessary, but permanent work can change the original conditions and affect documentation or claim review.
A roofer, exterior contractor or gutter specialist may complete the work. The written project scope should assign responsibility for removal, replacement and coordination.
Yes. If hail compromises roofing, flashing or another exterior opening, water may enter the building. Arrange exterior and interior assessments when water intrusion is found.
Next step
After a hailstorm, document the property safely and arrange qualified roof and siding inspections before permanent repairs begin. Keep each scope separate enough to understand, but coordinate shared flashing, gutters, access and scheduling.